Severe diseases or disabling conditions can make returning to work impossible, creating an urgent need for long-term financial security. Total and Permanent Disability (TPD) cover attached to superannuation offers a vital lump-sum insurance benefit designed to replace lost future earnings, fund ongoing care, and cover life’s essential living expenses.
Policyholders must thoroughly understand the superannuation disability payout framework to ensure eligible individuals receive their entitlements seamlessly without encountering unnecessary delays or policy rejections. Following proper legal procedures when navigating tpd insurance claims guarantees families receive the maximum lump-sum benefit outlined in their policy terms.
Deciphering Total Disability Definitions
There are two main legal definitions of a total disability under superannuation policies. It becomes clear that for ‘any occupation’ policies, there has to be evidence that a worker can’t undertake any occupation to which they are suited due to their education, training and experience. “Own occupation” policies demand proof that the person cannot carry out the duties of the job that he or she previously held before getting disabled.
Insurers assess claims based upon very detailed medical and work capacity criteria:
- Insurers evaluate transferable skills in various industries to determine a worker’s capacity to work.
- Two independent medical practitioner reports are the usual requirements for Medical Evidence.
- Claimants need to be off work for about 3-6 months before applying for waiting periods.
Essential Proof and Medical Documentation
Long claim delays can be avoided with complete evidence. Doctors’ reports, clinical histories, and tax records are closely reviewed by insurers to ensure work history and functional limitations are verified. More than 40% of the withdrawals of voluntary claims are due to missing medical information.
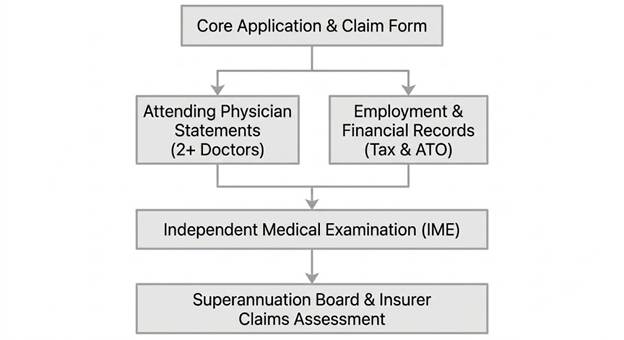
Structured functional capacity testing, along with clinical notes, provides insurance companies with a better understanding of restrictions in everyday activities that relate to physical or mental function.
Industry Payout Rates and Benchmarks
According to official APRA data, claims approval rates differ by insurance channel and type of medical condition.
| Claim Category / Channel | Acceptance Rate | Primary Risk Factor |
| Group Super Policies | ~86.4% | Strict Any Occupation threshold |
| Direct Individual Policies | ~77.4% | Non-disclosures in disputes |
| Disease-Related Claims | ~90.3% | Clear diagnostic imaging/testing |
| Mental Health Claims | ~83.1% | Fluctuating severity of symptoms |
| Musculoskeletal Claims | ~83.9% | Disputes regarding permanent disability |
More than two-thirds of claims that were initially rejected or disputed are overturned when specialist evidence is provided in support of a bad decision.
Navigating the Step-by-Step Process
A systematic approach minimizes administrative “hassle” in the review process:
Obtain policy timetables from all current and previous superannuation policies.
2. Verify that the person had active insurance coverage on the date of onset of injury or illness.
3. Obtain comprehensive clinical information from primary care physicians and specialists.
5. Fill in the preliminary claim paperwork with accuracy, outlining work history and skill levels.
5. Make sure that all documents are submitted and keep copies of all communication with insurers.
With tracking, claims will not stagnate during the insurer’s review periods.
Multiple Coverage of Super Funds
Frequently, people have several superannuation plans from different previous employers. One person may be able to claim on multiple TPD insurance claims that are active in various super funds for the same disabling event.
Claims are not excluded or denied when a claimant receives a lump sum payment from one fund and remains insured from the time of the disablement from the other fund. By scrutinising several policy terms, there is no fear of missing a legitimate lump sum entitlement.
Frequently Asked Questions
What amount of disability is considered total and permanent in superannuation?
A total and permanent disability is when a person is unable to work in a role that is consistent with their education, training or experience due to an illness or injury.
How long does a superannuation disability claim take to process?
The time to process a standard claim is 6-12 months. Applications with incomplete medical records or complex cases may take longer.
Is there a chance to make a claim for mental health issues?
Yes. If medical evidence demonstrates permanent inability to work, the following psychiatric conditions are considered to be qualifying depression: severe depression, anxiety, PTSD.
Does insurance benefit become taxable when it is received?
For disability benefits provided within superannuation, there are certain tax formulas based on eligibility periods of service and ages, but there may be tax-free benefits.
What are the consequences of a disabler’s denial?
Where a formal internal complaint is made, or the matter is taken to the Australian Financial Complaints Authority (AFCA), clinical evidence will be updated.
Securing Financial Independence
Superannuation disability benefit is a crucial financial cushion when life takes a turn for the worse. Proper preparation, medical reporting and systematic monitoring safeguard policyholders against typical application traps. When individuals have an understanding of rights within their superannuation policies, they have the confidence to go ahead with the claim process and ensure that they receive the lump sum support that they are entitled to.