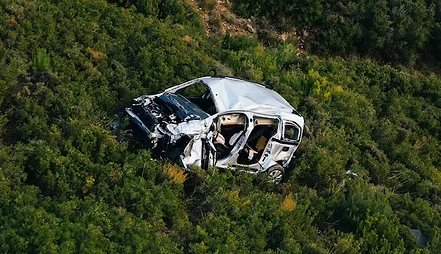
If your car was declared a total loss after an accident in Georgia, you have probably received a settlement offer from an insurance company that feels, in some vague but persistent way, too low. You are not alone in that feeling, and often you are not wrong either. Total loss claims in Georgia follow specific rules, but insurance companies still have room to make assumptions and estimates that work in their favor rather than yours. Understanding how these offers are calculated, and where the numbers commonly go wrong, can help you recognize a lowball offer and push back with confidence.
This guide walks through what a total loss designation actually means in Georgia, how insurers are supposed to calculate your vehicle’s value, and the specific red flags that suggest you are being shortchanged.
What “Total Loss” Means Under Georgia Law
In Georgia, a vehicle is typically considered a total loss when the cost of repairs, combined with the salvage value, meets or exceeds a certain percentage of the vehicle’s actual cash value (ACV). Georgia does not use a single rigid statutory threshold the way some states do; instead, insurance companies apply their own total loss formulas, which generally fall somewhere between 70 and 100 percent of the vehicle’s pre-accident value. If the numbers cross that threshold, the insurer will usually declare the car a total loss rather than pay for repairs.
Once that determination is made, the insurance company owes you the actual cash value of the vehicle immediately before the accident, minus your deductible if you are claiming through your own collision coverage. That actual cash value is where most disputes begin, because ACV is not a fixed number. It is an estimate, and estimates can be manipulated.
How Insurers Calculate Actual Cash Value
Insurance companies in Georgia typically use third-party valuation software, such as CCC, Mitchell, or Audatex, to generate a report estimating your car’s pre-accident value. These programs pull data from recent sales of comparable vehicles, adjust for mileage, condition, options, and location, and spit out a number that becomes the basis for the settlement offer.
The problem is that these systems are only as accurate as the data fed into them, and insurers sometimes apply adjustments that quietly reduce the final figure. Common tactics include:
Using comparable vehicles that are not truly comparable, such as cars with significantly higher mileage, missing features, or from different parts of the state where prices run lower.
Applying a “condition adjustment” that assumes your car needed cosmetic or mechanical work it did not actually need.
Failing to include the value of aftermarket upgrades, recent repairs, or new tires and batteries.
Averaging in private-party listings or auction prices that reflect a lower selling environment, instead of dealer retail prices, which is the standard Georgia law expects insurers to use.
Because the valuation report looks official and data-driven, many drivers assume the number is accurate and do not question it. That assumption is exactly what allows lowball offers to go unchallenged.
Red Flags That Suggest Your Offer Is Too Low
There is no single formula for spotting a bad offer, but a few patterns show up again and again in total loss claims in Georgia.
The Comparable Vehicles Do Not Match Your Car
Ask your insurer for the full valuation report, not just the summary. It should list specific comparable vehicles used to calculate your ACV. Check the mileage, trim level, options, and condition of each one against your own vehicle. If the comparables have significantly more mileage, fewer features, or are listed as “fair” condition when your car was in excellent shape, the resulting valuation will be artificially low.
Your Car’s Upgrades and Recent Work Were Ignored
If you had recently replaced tires, installed a new battery, added aftermarket wheels or stereo equipment, or completed major maintenance like a new transmission, these additions should increase your car’s value. Insurers frequently leave this information out unless you specifically provide documentation and request that it be factored in.
The Offer Does Not Reflect Local Market Prices
Georgia is a large state with real price differences between metro Atlanta, mid-size cities like Savannah or Augusta, and rural areas. A valuation that pulls comparable sales from a lower-cost region, when your car was located and would have been sold in a higher-cost market, can shave hundreds or even thousands of dollars off a fair offer.
There Is a Vague “Condition Adjustment” Deduction
Some reports include a flat percentage deduction for “condition” without a clear explanation. If you cannot get a straight answer about what specific damage or wear justified the deduction, it is reasonable to push back and ask for documentation.
The Offer Came Very Quickly After the Accident
A fast offer is not automatically a bad one, but insurers sometimes hope that an initial lowball number will be accepted before the policyholder has time to research their car’s actual value. If you received a number within a day or two of the total loss determination, take the time to verify it independently before signing anything.
How to Independently Verify Your Car’s Value
Before accepting or disputing an offer, it helps to build your own estimate using sources the insurance company cannot easily dismiss.
Start with major used car valuation tools like Kelley Blue Book and NADA Guides (now part of J.D. Power), entering your car’s exact trim, mileage, and condition. These tools are widely recognized and give you a point of comparison against the insurer’s number.
Search local dealership listings and marketplace sites for vehicles that closely match yours in year, make, model, trim, and mileage. Save screenshots of these listings with dates, since prices change and you want a record of what the market looked like at the time of your accident.
Gather any receipts or records for upgrades, recent repairs, or new parts. Insurance adjusters are far more likely to factor these in when you provide documentation rather than simply asserting the work was done.
If you have access to a vehicle history report, such as a Carfax, pull it to confirm there were no prior accidents or title issues that the insurer might otherwise assume existed.
What to Do if You Believe the Offer Is Too Low
If your research suggests the insurer’s number is below fair market value, you have options, and Georgia law gives you some leverage.
Request the Full Valuation Report in Writing
You are entitled to see the detailed breakdown behind your settlement offer, not just the headline number. Ask specifically for the comparable vehicles used, any condition adjustments applied, and the source of the data.
Submit a Written Rebuttal With Evidence
Put together your own comparable listings, documentation of upgrades, and any other supporting evidence, and submit it formally to the claims adjuster. Be specific about which comparables you believe are flawed and why, rather than simply stating that the offer feels low.
Ask About the Appraisal Clause in Your Policy
Many Georgia auto insurance policies include an appraisal clause, which allows either party to demand an independent appraisal process if they disagree on value. This typically involves each side hiring an appraiser, and if those two cannot agree, a neutral umpire resolves the dispute. This process can be faster and less expensive than a lawsuit.
File a Complaint With the Georgia Office of Insurance and Safety Fire Commissioner
If you believe the insurer is acting in bad faith or refusing to provide a reasonable explanation for its valuation, Georgia’s Office of Insurance and Safety Fire Commissioner accepts consumer complaints and can sometimes prompt a review of how your claim was handled.
Consult an Attorney for Larger or Disputed Claims
For higher-value vehicles, or in cases where the insurer is being unresponsive or appears to be acting in bad faith, consulting an attorney who handles total loss and insurance disputes in Georgia can be worthwhile. Many offer free consultations and only get paid if they recover additional money on your behalf.
Special Considerations for Leased or Financed Vehicles
If your totaled vehicle was leased or still had a loan balance, the math gets more complicated. The insurance payout goes toward satisfying the loan or lease payoff amount first, and if the ACV is lower than what you owe, you could be left paying the difference out of pocket unless you had gap insurance. This makes it even more important to verify the fairness of the ACV offer, since a lowball valuation does not just cost you money; it can leave you owing on a car you no longer have. If you carry gap coverage, review your policy to confirm whether it covers the specific shortfall you are facing, since some policies have limits or exclusions for excess mileage or prior damage.
Common Mistakes Drivers Make When Accepting Offers
A surprising number of drivers accept the first offer simply because they want the claim resolved quickly, especially if they need funds to buy a replacement vehicle. Others assume that because the valuation came from standardized software, it must be accurate and are not aware they have the right to challenge it. Some drivers also sign a release of all claims without realizing that doing so forecloses any future negotiation, even if they later discover the offer was too low. Reading the fine print before signing, and resisting pressure to settle immediately, protects your ability to negotiate.
Frequently Asked Questions
How long do I have to dispute a total loss offer in Georgia?
There is no single fixed deadline written into Georgia insurance law for disputing an offer, but you should act quickly. Most policies and claims processes expect a response within a reasonable window, often a few weeks, so gather your evidence and respond in writing as soon as possible.
Can I keep my car if it is declared a total loss?
Yes, in many cases. You can choose to keep the vehicle, but the insurer will subtract the salvage value from your settlement, and you will typically receive a salvage title, which affects future resale and insurability.
Does Georgia require insurers to use a specific valuation method?
Georgia does not mandate one specific valuation method, but insurers are expected to use fair market value based on comparable vehicles, and regulators can review complaints if a company’s methodology appears unreasonable.
What if I still owe more on my loan than the settlement offer?
This is called being “upside down” on the loan. If you do not have gap insurance, you may be responsible for the remaining balance. Review your loan and gap coverage terms carefully, and factor this into your negotiation strategy.
Is it worth hiring an attorney for a total loss dispute?
For lower-value vehicles, many drivers successfully negotiate on their own using independent valuations. For higher-value vehicles or cases involving bad faith tactics, an attorney consultation is often worth the time, especially since many work on contingency.
What documents should I keep throughout the claims process?
Keep the following:
- The insurer’s full valuation report
- Your own comparable vehicle listings with dates
- Receipts for upgrades or recent repairs
- Any written correspondence with the adjuster
- A copy of your insurance policy, including the appraisal clause
Final Thoughts on Protecting Your Settlement
Total loss claims in Georgia can feel like a one-sided process, where a software-generated number arrives, and you are expected to simply accept it. In reality, you have more leverage than most drivers realize. By requesting the full valuation report, independently verifying your car’s market value, documenting upgrades and repairs, and understanding your policy’s appraisal rights, you put yourself in a much stronger position to push back on a lowball offer. Taking the time to verify the numbers before signing anything is one of the simplest ways to make sure you receive a fair and accurate settlement for your vehicle.